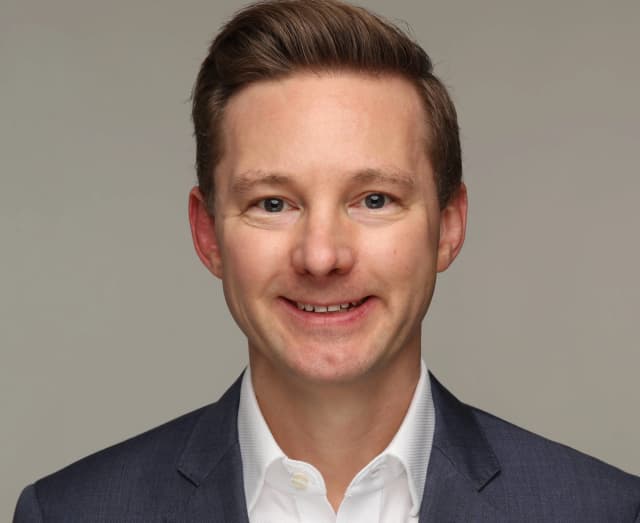
Christopher Schildt
The founder

Christopher Schildt

Christopher Schildt is a senior advisor to a RegTech startup and a Visiting Senior Fellow at the London School of Economics. He spent 20+ years in operational and leadership roles at the CIA, Uber, and Coinbase, co-founded The Fintel Group, a US financial planning company, and held the Series 65 investment adviser licence. He holds a BA in economics from Yale University, an MPA in economic policy from Princeton University, and an MBA from the University of Oxford.

Read why I built 100 Great Years →

Our Core Philosophy

01
Autonomy, not accumulation.

A great life isn't about the size of your bank account — it's the time and freedom to spend it on what matters. Health and wealth exist to buy back your time, not to be stockpiled.

02
Health and wealth are one system, not two.

Financial stress erodes health. Poor health erodes earning power and independence. We treat them together because they were never actually separate.

03
Wealth means enough, not rich.

We track Wealthspan — whether your money covers the life you want — not net worth, which turns into an obsession with a number instead of a life.

04
Be proactive, not reactive.

Public healthcare underfunds prevention; for-profit healthcare profits from treating you after you're sick. Either way, no one else is managing your health years before you'll need it — technology now lets you do it yourself.

05
The quiet decision, repeated.

We don't chase biohacks or market timing. The best decision you make for your health and your wealth isn't the dramatic one — it's the quiet one you make again tomorrow.

06
Preparation, not fear.

Markets fall. Bodies age. Tomorrow’s autonomy depends on the reserves you build today.

Methodology

Every projection — accumulation, drawdown, or a historical replay — runs the same recursion, once per month, from your current age to 100:

V(n+1) = V(n) × (1 + r(n)) + C(n)
V(n)
Portfolio value at month n
r(n)
The real monthly rate of return applied that month
C(n)
Net cash flow that month: positive when saving, negative when drawing down

This is also the exact calculation the AI Coach runs whenever you ask it about your future finances — it never does the math itself, it calls this same code every time. More on why, in the AI Usage Policy.

Everything below describes how r(n) and C(n) get their values.

What’s included — and what isn’t

Included
  • Savings & Investments balances
  • Income Streams — salary, pensions, rental income, benefits, State Pension/Social Security
  • Recurring debt payments, as a cash-flow reduction
  • Planned one-off expenses
Excluded
  • Other Assets — property, business equity, crypto, collectibles
  • Outstanding debt balances — never netted against portfolio value

Other Assets stay off this curve deliberately. Wealthspan asks one specific question — will your liquid capital cover your spending? — and an asset you can’t readily draw down to pay a bill doesn’t answer it.

Debt

Debt is modelled as cash flow, not as a balance-sheet offset. Each debt’s monthly payment reduces your spending total, which reduces your surplus, which reduces what compounds. Once a debt is paid off, its payment drops out and your surplus rises accordingly. The model never subtracts your outstanding debt balance from your portfolio value — Wealthspan tracks what you’re building, not your net worth.

Tax

Income is taxed by type, not by age or retirement status:

take-home earned = (earned income − pension contribution) × (1 − earned-income tax rate)
net other income = other income × (1 − other-income tax rate)
net cash = take-home earned + net other income − spending

Pension contributions come out of earned income before tax — the way they actually work — then get added back untaxed to your monthly total, since they’re going into your investments rather than your spending.

Monthly surplus and shortfall

if net cash ≥ 0:  C(n) = net cash + pension contribution (surplus — invested)
if net cash < 0:  C(n) = pension contribution − (|net cash| ÷ (1 − other-income tax rate)) (shortfall — grossed up for tax, then withdrawn)

Withdrawing £1,000 net from a portfolio doesn’t cost the portfolio £1,000 — it costs however much needs to be sold to net £1,000 after tax. The model accounts for that at every age, so working an extra year never looks artificially better or worse than reality.

Rate of return

You choose one of three allocation tiers, each a fixed real (inflation-adjusted) annual rate, converted to a monthly rate: Conservative (3%), Balanced (5%), Growth (7%). Where we hold your actual portfolio allocation, we pre-select the tier that matches it.

That headline rate is then discounted by the share of your portfolio currently held in cash — cash isn’t earning the same return as cash invested, so it’s excluded from the growth calculation, not double-counted. One honest limitation worth stating: this cash percentage is a snapshot, taken once from your current holdings, not something the model re-checks month by month. A 50-year projection therefore assumes your cash allocation today stays constant for the rest of your life. It’s a simplification, not a forecast of your future rebalancing decisions.

Inflation

The model runs in real terms throughout. Anything you enter is treated as today’s money and stays level in real terms unless marked as inflation-linked, in which case it grows at an assumed 2.5% a year. This keeps the projection in comparable, today’s-money terms rather than mixing inflated future numbers with current ones.

Historical backtesting

Rather than assuming one fixed return every year, the same equation runs again — 95 separate times — using real historical returns instead of a flat rate: 152 years of US stock market data (1871–2022) and 98 years of US bond data (1928–2025), from two established academic datasets. For blended stock/bond scenarios, the model uses the 95 years both datasets share (1928–2022), starting your exact plan from every one of those years — so you can see how it would have held up starting in the Depression, the 1970s, or 2008, not just an “average” year.

The stock series is adjusted down by 2.3 percentage points a year, reflecting that US markets have historically outperformed the rest of the world’s by roughly that margin — so the projection doesn’t quietly assume uniquely strong US returns forever.

This modelling is currently based on US market history.

The core method

Every survival curve in the product — whether the interactive chart in the Healthspan widget or the single headline number on your Home tab — starts from the same actuarial transformation:

S_adjusted(x) = S(x)HR
S(x)
The population's baseline probability of surviving to age x, from national life tables (ONS in the UK, CDC in the US, WHO elsewhere), matched to your age and sex
HR
The published hazard ratio for a given health behaviour, drawn from peer-reviewed research (see Research, below, for the specific studies)

In plain terms: S_adjusted(x) is the number the whole equation is solving for — your own adjusted chance of surviving to a given age x, once one specific habit has been factored in. It’s what actually gets plotted on the curve, at every age from where you are now to 100.

The right side says how to get there: take the population baseline, S(x), and raise it to the power of HR. Raising a number to a power isn’t multiplication — it’s a stronger kind of scaling, and here it works like a dial. An HR below 1 (say, 0.5 — half the population’s risk) pushes your adjusted survival curve above the baseline. An HR above 1 (say, 1.5 — 50% higher risk) pushes it below the baseline. An HR of exactly 1 leaves the baseline exactly where it is.

This is the standard method actuaries and epidemiologists use to adjust a baseline survival curve for a single risk factor. Every curve you see is this same equation, run against your own current habits.

Why we only show one variable at a time

Multiplying several hazard ratios together — say, your VO2 max hazard ratio times your sleep hazard ratio — technically produces a number. But doing that assumes the two risk factors act entirely independently of each other, with no interaction at all. That assumption isn’t something the research actually supports with enough precision to model responsibly. Real risk factors interact in ways the literature hasn’t fully quantified.

So rather than combine everything into one falsely precise “your total adjusted lifespan,” the interactive chart shows one variable’s effect at a time, clearly labelled, against the population baseline. It’s a deliberate trade-off: less impressive-looking at first glance, considerably more honest about what the evidence can actually support.

How this becomes your Home tab’s Lifespan Outlook

The Lifespan Outlook figure on your Home tab runs the identical equation across every health variable we can measure or reasonably estimate for you, and surfaces the single one currently furthest from the population average — for better or worse — as a signed number of years, alongside a plain sentence naming what’s driving it (“Your consistent strength training is associated with a longer-than-average lifespan,” for example). It’s the same evidence, the same maths, and the same population baseline as the full interactive chart — just collapsed to the one number and one sentence that’s most useful at a glance, rather than the full picture the widget itself gives you.

What none of this is

Not a diagnosis. Not a personal life-expectancy prediction. It’s population-level evidence, applied honestly to your own tracked and self-reported data — a way to see where your habits sit relative to people like you, not a forecast of your actual future.

Every health domain is built on named, peer-reviewed sources — not wellness-blog consensus. A sample, grouped by module:

Cardiorespiratory fitness
Mandsager et al., JAMA Network Open, 2018 (122,000+ patients) — fitness level and all-cause mortality
Strength & muscle mass
Leong et al., Lancet, 2015 (2M+ participants) on grip strength; Saeidifard et al., European Journal of Preventive Cardiology, 2019 on resistance training; Dodds et al., 2016 (UK Biobank) for grip-strength norms by age and sex
Sleep
Cappuccio et al., Sleep, 2010 (1.3M participants) — sleep duration and mortality
Mental wellbeing
WHO-5 (World Health Organization), SRMH (canonical wording from NIH/CDC), ONS4 (UK Office for National Statistics) — validated instruments, not custom questions
Cardiovascular risk
QRISK3 (UK) and the ACC/AHA Pooled Cohort Equations / Framingham (US) — the same tools used in clinical practice on both sides of the Atlantic
Retirement income
Bengen's original safe-withdrawal-rate research (1994) and the Trinity Study (Cooley, Hubbard & Walz, 1998), later refined by Pfau, Kitces, and Finke/Pfau/Blanchett on sequence-of-returns risk

The Coach doesn’t rely on the AI to notice things on its own. A separate, deterministic rules engine runs across your logged data first — the same fixed logic, every time, for every user — looking for 80+ patterns both within a single area (a declining sleep trend alongside rising stress) and across health and wealth together (financial stress coinciding with a drop in sleep quality). The AI is told what was already found; it doesn’t invent the finding. Pattern detection is code you could audit line by line. Pattern explanation is where the AI adds value.

A note on what this is — and isn’t

Your Wealthspan projection is a model built from your own inputs and historical data — it’s not a prediction of your actual future. Your Healthspan score is informational, not a diagnosis. Nothing here is regulated financial advice or medical advice. For anything specific to your own situation, talk to a qualified financial adviser or doctor — the same standard the AI Coach itself holds to whenever a conversation calls for it.

AI Usage Policy

We understand the growing public pushback against AI. We believe, however, that the pushback isn’t about AI’s capabilities — it’s the dishonesty behind its use. 100 Great Years only works if it earns your trust, so this policy sets out exactly how, where, and why we use AI.

Area
AI’s role
Human’s role
AreaSoftware Development
AI’s roleClaude.ai drafts specifications; Claude Code implements them; ChatGPT independently challenges critical decisions
Human’s roleChris reviews every spec, approves every checkpoint, and manually tests every change
AreaAI Coach
AI’s roleResponds using a fixed set of guardrails — never a diagnosis, never a raw numeric score, never an invented statistic — and hands off automatically to real crisis resources if self-harm ever comes up
Human’s roleYou can ask the Coach to explain its own rules, any time
AreaLearn / Blog Articles
AI’s role>95% written by Claude.ai from sourced material
Human’s roleEvery article reviewed, edited, and approved by Chris before publishing
AreaFounders Journal
AI’s roleLight editing pass only
Human’s role>95% written by Chris — these are opinion and story, not foundational knowledge
AreaWebsite Home Page
AI’s role~25% Claude.ai, with ChatGPT challenging decisions
Human’s role~75% written by Chris
AreaImages
AI’s rolePrompts generated by ChatGPT, images generated by Gemini
Human’s roleChris selects and approves every image used

Sourcing standard: every Learn/Blog article draws only from peer-reviewed journals and major health or financial institutions — never wellness blogs, supplement-brand marketing, or news articles citing other news articles.

Every number the Coach gives you comes from code, not a guess. Pattern Detection — covered in Methodology, above — runs a fixed set of rules across your data before the AI ever responds. And every calculation the Coach references, from your Wealthspan projection to your cardiovascular risk score, runs through the same deterministic formulas covered in Methodology — not language-model arithmetic. The AI explains what the code found. It doesn’t invent the finding, and it doesn’t do the maths itself.

Read exactly how we use AI →

Founders Journal

A running record of the thinking, and the occasional stumble, behind 100 Great Years — written by me, not AI.